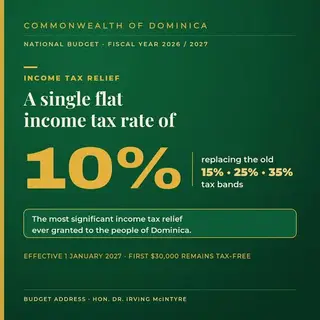
Parliament has passed amendments to the Income Tax Act introducing a flat personal income tax rate of 10 per cent from January 2027. The amendments also provide incentives for job creation, business disaster preparedness and investment in commercial rental properties.
Minister for Finance, Honourable Dr. Irving McIntyre, told Parliament that the personal income tax changes would increase take-home pay for individuals who currently pay income tax, providing recurring benefits to households and supporting spending in the economy.
He said the measures would give taxpayers additional income to meet their families’ needs and encouraged beneficiaries to use the savings wisely.
For businesses, the amendments provide for approved Business Vulnerability Funds, allowing companies to set aside up to 0.5 per cent of gross annual sales for disaster recovery and deduct those contributions from taxable income for the relevant year.
Businesses may accumulate tax-free savings up to the net book value of their insurable assets. The funds will be subject to approval and monitoring by the Comptroller of Inland Revenue. Withdrawals require the Comptroller’s permission, and any amount withdrawn without approval will be treated as taxable income.
Dr. McIntyre said the initiative would help businesses prepare for disasters and provide access to funds when operations and sales are disrupted.
The legislation also reintroduces an employment tax rebate for a two-year period beginning October 1, 2026. Employers can receive a rebate of two per cent of salary, up to $600 for each additional job created and filled, subject to a maximum annual rebate of $10,000 per employer.
The Minister emphasised that the incentive provides a tax rebate rather than a deduction from taxable income, rewarding businesses for creating additional employment.
A further amendment introduces an annual deduction for qualifying expenditure on buildings constructed or substantially reconstructed for commercial rental.
From income year 2027, eligible owners may claim three per cent of qualifying expenditure, capped at $30,000 annually, within the applicable ten-year period after the building was made available for rent.
Dr. McIntyre said this measure followed concerns raised during pre-Budget consultations about the tax treatment of commercial rental properties.
The amendments form part of Government’s efforts to increase disposable income, encourage private sector investment and employment, and strengthen the capacity of businesses to recover from disasters.